Speeding up infrastructure development and improving ease of doing business and vocational training are among things Vietnam should do to make itself more attractive to foreign investors post-COVID-19, according to investment fund VinaCapital.

Don Lam, the fund’s co-founder and CEO, said, “Consultants expect 20% of China’s manufacturing sector to move out the country in the coming years.
“Not all of that will come to Vietnam, but the country stands to attract a good portion of that for several reasons.”
They included factory wages in the country being less than half of those in China though the quality of the workforces is comparable, Vietnam doing an outstanding job in controlling the COVID-19 outbreak and ranking high in various FDI decision making schemes that companies use to evaluate the potential of a country for building factories.
Companies looked for some key factors when considering direct investment in a country.
They wanted good supply of labour with skills and experience, logistics convenience in places they set up new factories so that they could easily ship in raw materials and ship out finished products, minimal bureaucratic obstacles to setting up and operating factories, and political and economic stability.
Vietnam scored well in most of these aspects, and quickly improves in areas it did not.
But there were several things it could do to become more attractive to investors.
Its logistics costs continued to be high, and it needed to quickly build and improve physical infrastructure to rise in the World Bank Logistics Performance Index from its current 45th position.
The Government also needed to improve the country’s position in the World Bank’s ease of doing business rankings by streamlining the bureaucratic processes related to setting up and operating a business.
“In the most recent World Bank survey, Vietnam ranks 70th out of 190 countries, ahead of countries like Indonesia, and the Philippines but behind Malaysia and Thailand.”
The Government’s recently announced ‘fast track’ initiative to speed up the licensing of FDI projects was a good example of the steps it could take to reduce red tape and bureaucratic hurdles companies faced.
The Government should consider promoting quality FDI by setting up an Investment Promotion Agency (IPA) to actively market Vietnam advantages as an FDI destination around the world.
The Government tended to approach FDI reactively and only worked with foreign companies that approached it though the Ministry of Planning and Investment and other relevant Government departments had become more aggressive in following potential leads.
Next, Vietnam’s vocational training needs to be significantly improved to ensure that the workforce could perform tasks that require higher skill levels, and the country needed to invest in R&D and improve technical universities.
Finally, the Government could encourage the formation of industrial clusters around desirable industries such as electronics.
This strategy would have the dual advantage of maximising Vietnam’s benefit from FDI investments and giving firms more confidence to locate their higher value-added activities in the country.
According to VinaCapital, Free Trade Agreements help attract FDI to a country, especially when they entail measures that improve a country’s ease of doing business. However, it is important to note that Vietnam is already a party to more FTAs than any country in the world, it said.
Lam said, “Often countries use a range of tax incentives to attract foreign investment, and of course who does not like tax incentives? But offering overly generous tax breaks is not critical for Vietnam to be successful in attracting FDI.”
According to the IMF, tax incentives are “not critical” to attracting FDI and “…cannot substitute for political stability, good macroeconomic fundamentals, the availability of infrastructure, and a sound legal framework.”
Lam said his fund expected the next wave of FDI to be driven by companies relocating their factories out of China and have a bigger impact on Vietnam’s economy than previous inflows because multinational companies now had an incentive to help local firms “move up the value chain” to build supply chains in Vietnam capable of supporting those companies.
Under Document No. 10065/VPCP-KGVX, the Deputy PM agreed with proposals by the Ministry of Home Affairs for a one-day holiday for Vietnamese Culture Day in 2026, and a seven-day Tet holiday and a four-day National Day holiday in 2027.
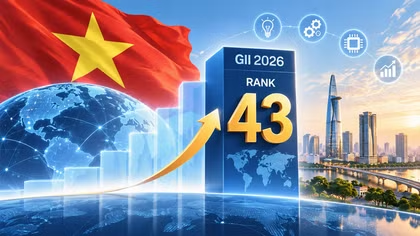
By 2030, Vietnam aims to rank among the world’s top 40 in the GII; raise total social investment in R&D to at least 2% of GDP, with non-State funding accounting for over 60%; increase international scientific publications by an average of 10% annually; and raise the number of patent applications and granted patents by an average of 16-18% annually.
The State Bank of Vietnam set the daily reference exchange rate at 25,624 VND/USD on October1, down 3 VND from the previous day.
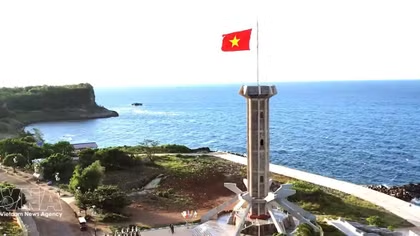
Quang Ninh's GRDP grew 15.04% in the third quarter, also leading the country.
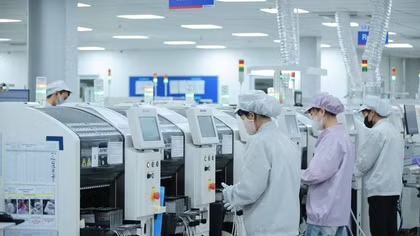
Vietnam needs flexible incentives and specialised green financial instruments, stronger inter-sectoral coordination, improved local governance capacity and a more complete MRV data system, said Ramla Khalidi, Resident Representative of the United Nations Development Programme (UNDP) in Vietnam.
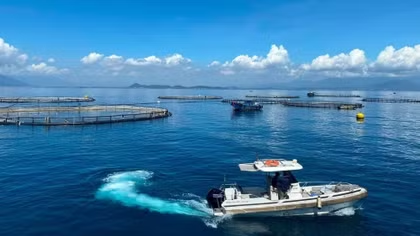
As the country enters a new development phase with greater demands for stronger marine-economy growth, institutional bottlenecks have emerged and need to be addressed.
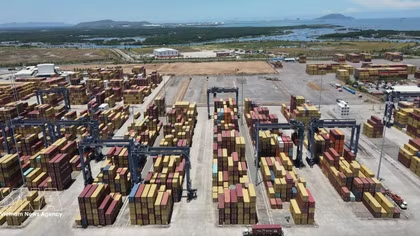
Experts from the Institute of Vietnam and World Economy under the Vietnam Academy of Social Sciences noted the quality of recent growth as the high growth rate has been recorded against an increasingly higher comparative base.
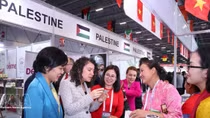
Vietnam's Halal exports remain modest at around 900 million USD a year, accounting for less than 1% of the global market. Most exports are still raw agricultural and seafood products. Only around 1,000–1,300 Vietnamese businesses obtained or maintained Halal certification during 2024–2026.
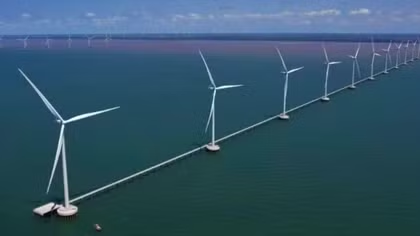
Vietnam needs a comprehensive policy framework to remove legal and procedural bottlenecks and create conditions for offshore wind power projects to access long-term investment capital, helping to unlock the country’s substantial offshore wind potential, said insiders.
Under a decision of the municipal People’s Committee on establishing an inter-agency working group, departments and agencies are responsible for identifying facilities subject to greenhouse gas inventories, developing emissions-reduction plans and studying projects capable of generating carbon credits.
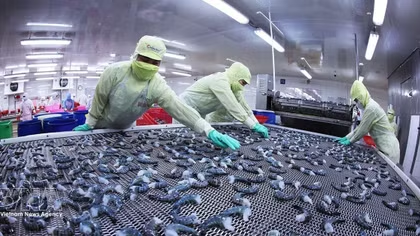
According to data from the Vietnam Customs cited by the Vietnam Association of Seafood Exporters and Producers (VASEP), shrimp exports reached 478.5 million USD in August, up 4.2% from the same month last year. The eight-month total stood at 3.3 billion USD, representing a year-on-year increase of 12%.
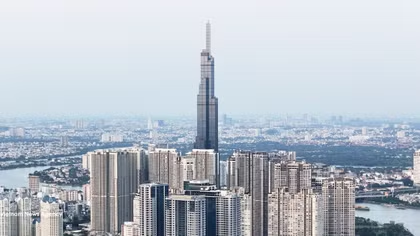
Vietnam is seen as a potential market, with considerable room for growth in real estate, particularly commercial property, compared with some regional markets. Strong Vietnam-Russia ties and opportunities to establish foreign-invested enterprises are also considered favourable for Russian investors.
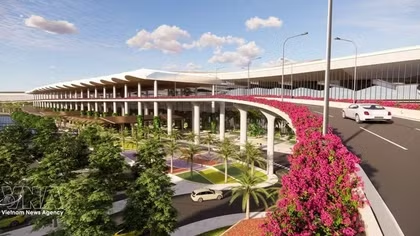
For 2021-2030, the Civil Aviation Authority of Vietnam proposed bringing forward the investment in a parallel taxiway system and a connecting taxiway north of Runway No. 2 at Phu Quoc International Airport, in order to connect with the aircraft maintenance and repair facility (hangar) planned for the northern area of the airport.
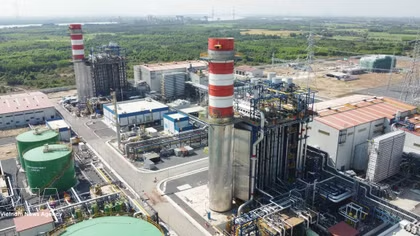
For LNG-fired power to fulfill its role in Vietnam’s energy transition, bottlenecks in institutions, infrastructure, electricity pricing, PPAs, power dispatch and financing must be addressed together.
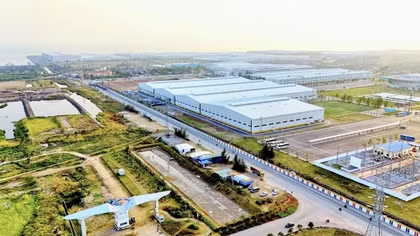
From policy and infrastructure to industrial real estate, Vietnam’s FDI advantages are broadening towards a more integrated production ecosystem, offering investors a stronger combination of conditions for high-value, technology-intensive and long-term projects.
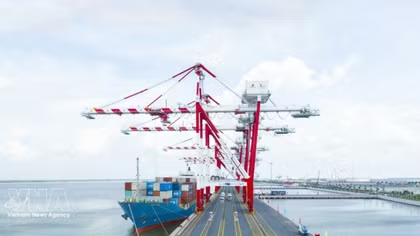
As trade expands, systemic bottlenecks across transport networks, warehousing, ports, border gates, and industrial zones are becoming more apparent. Experts emphasise the need to shift from a fragmented, project-by-project approach toward strategic management structured around trade corridors and integrated supply chains.
The company will buy non-performing loans from credit institutions and foreign bank branches, recover and dispose of debts and collateral, restructure loans and support lenders in resolving bad debts.
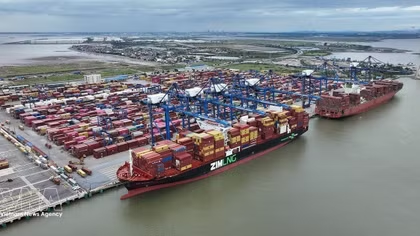
Do Ngoc Hung, Trade Counsellor and head of the Vietnam Trade Office in the US, said what stands out is not only the growth in trade volume but also the increasingly deep economic ties between the two countries.
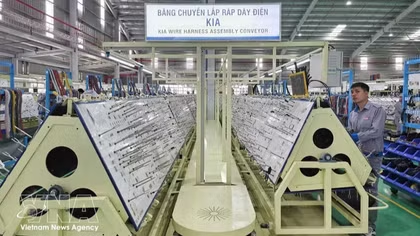
According to the Ministry of Finance, State budget revenue in the first eight months of 2026 was estimated at 2.02 quadrillion VND (77.7 billion USD), equivalent to 80% of the annual estimate and up 16% year-on-year. Domestic revenue reached 1.75 quadrillion VND, accounting for 86.6% of total revenue and rising 16.6%.
Hanoi aims to achieve average annual export growth of at least 12% during 2026-30, with the city seeking to diversify export markets, boost high-tech and value-added products and reduce reliance on traditional markets.