Why State Bank of Vietnam has kept deposit rates unchanged

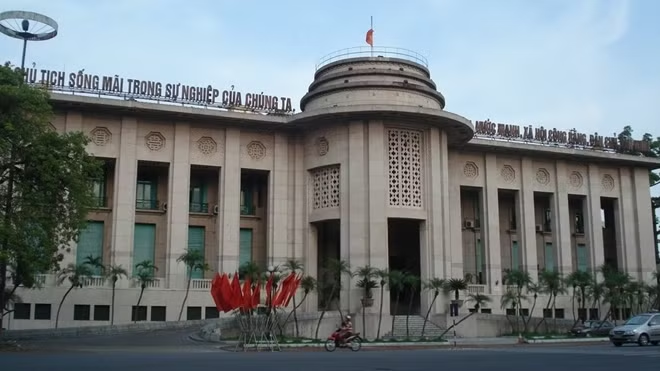
The State Bank of Vietnam has recently decided to lower the interest rates on short-term loans to priority sectors by 0.5 percentage points and some policy rates by 0.25 percentage points.

This move is beneficial to the business community but there is still much to be discussed over this decision. In an interview, Can Van Luc, a member of the National Financial and Monetary Policy Advisory Council, offered his insights into the central bank’s move.

Q: Why did the State Bank decide to refrain from cutting deposit rates?

A: I think the State Bank has a good reason for not adjusting deposit rates because if cuts are made, money will flow to other channels, possibly gold, stocks or property. This move would be very risky and cause difficulty for banks to mobilise funds especially when the amount of deposits was not very high in the first six months of the year.
Q: Why did the State Bank opt for a reduction in interest rates on loans to five priority sectors at just 0.5 percentage points rather than a larger cut?

A: The National Financial and Monetary Policy Advisory Council met and discussed the issue thoroughly and recommended that level of reduction as a deeper cut would please enterprises but could also have other implications.

Firstly, banks would be hesitant to lend to priority sectors because the interest rates were too low.

And secondly, the difference between deposit and lending rates in Vietnam is around 2 percentage points while the gap is much higher in the region, about 3 points in China and about 4 points in Indonesia and the Philippines.

The banking system cannot deal with a larger cut, given the ratio of non-performing loans remains high.

Q: So why did the State Bank have to intervene with administrative measures instead of just letting the market adjust interest rates automatically?

A: I myself have repeatedly suggested scrapping the ceiling interest rates but I understand that in the current context, there are still many vulnerabilities and risks, so administrative measures still have to be taken.

If the State Bank did not use administrative measures, it would be difficult to adjust the interest rates. Of course, competition has become more intense in the banking system. If there are good projects and business plans, there will always be funds available with attractive interest rates.

Q: Some say that such rate cuts will lead to overwhelming credit growth. Do you think it is a problem in the current context?

A: I think credit is unable to grow so fast as the cuts are made only to five priority sectors while credit growth in these sectors is not too high. I think by all means the State Bank will restrict credit growth at 17-18% and will ensure it doesn’t exceed 20% since the IMF and some experts have cautioned the central bank against overheated credit growth.

Basically, liquidity of the banking system is still good and the loan-to-deposit ratio is safe. However, if credit grows too fast and there are insufficient deposits, it will cause liquidity problems for banks and won’t be unable to fully support growth. Credit growth should not be higher than 18%.

The problem now is how to mobilise funds, which certainly involves gold and the US dollar.

Q: What do think are the solutions to the problem of mobilising funds?

A: To help banks lower interest rates, I suggest that the State Bank first expedite the progress of resolving bad debt. There are only five years for such measures to be implemented, otherwise it will be too late.

Secondly, the State Bank should consider revising the document known as Circular 06 issued last year on prudent ratios in the operations of credit institutions. The circular allows banks to use 50% of their short-term funds for medium and long-term loans this year and 40% next year. This means the banking system will use fewer short-term funds for medium and long-term loans next year.

That is why the banking system now has to speed up the mobilisation of medium and long-term funds to meet requirements of next year. If so, the banking system has to guarantee capital for medium and long-term loans while also having to mobilise funds to achieve the credit growth target of 18% this year.

If the above-mentioned circular is amended, the demand for medium and long-term funds will be met, thereby easing the race for deposit rates and helping to reduce lending rates.

I also suggest adjusting the ceiling rate for USD deposits because the demand for foreign currency this year is higher than last year.

Besides the issue of trade deficit, loans in foreign currency rose about 5% in the first half of 2017 while the increase stood at only 1.5-2% last year. It is apparent that Vietnam’s economy still has a high demand for foreign currency.

For the meantime domestic banks must borrow USD from foreign banks at around 2.5%, and if we raise the USD deposit rate by 0.25 percentage points to mobilise USD from the people, the borrowing costs will be much lower. It will also help to reduce lending rates.

Moreover, measures are needed in the long run to mobilise gold held by the public to boost the economy. It is also a way to reduce the pressure on Vietnamese dong interest rates.
NDO

Other News

Vietnam accelerates innovation to boost growth, competitiveness

Vietnam accelerates innovation to boost growth, competitiveness

By 2030, Vietnam aims to rank among the world’s top 40 in the GII; raise total social investment in R&D to at least 2% of GDP, with non-State funding accounting for over 60%; increase international scientific publications by an average of 10% annually; and raise the number of patent applications and granted patents by an average of 16-18% annually.

Vietnam sees high growth prospects

Vietnam sees high growth prospects

Experts from the Institute of Vietnam and World Economy under the Vietnam Academy of Social Sciences noted the quality of recent growth as the high growth rate has been recorded against an increasingly higher comparative base.

Vietnam seeks bigger share of global Halal market

Vietnam seeks bigger share of global Halal market

Vietnam's Halal exports remain modest at around 900 million USD a year, accounting for less than 1% of the global market. Most exports are still raw agricultural and seafood products. Only around 1,000–1,300 Vietnamese businesses obtained or maintained Halal certification during 2024–2026.

Hanoi sets up inter-agency mechanism to operate carbon market

Hanoi sets up inter-agency mechanism to operate carbon market

Under a decision of the municipal People’s Committee on establishing an inter-agency working group, departments and agencies are responsible for identifying facilities subject to greenhouse gas inventories, developing emissions-reduction plans and studying projects capable of generating carbon credits.

Shrimp exports reach 3.3 billion USD in eight months

Shrimp exports reach 3.3 billion USD in eight months

According to data from the Vietnam Customs cited by the Vietnam Association of Seafood Exporters and Producers (VASEP), shrimp exports reached 478.5 million USD in August, up 4.2% from the same month last year. The eight-month total stood at 3.3 billion USD, representing a year-on-year increase of 12%.

Russian investors explore opportunities in Vietnam's real estate market

Russian investors explore opportunities in Vietnam's real estate market

Vietnam is seen as a potential market, with considerable room for growth in real estate, particularly commercial property, compared with some regional markets. Strong Vietnam-Russia ties and opportunities to establish foreign-invested enterprises are also considered favourable for Russian investors.

Phu Quoc airport planning adjusted to serve APEC 2027

Phu Quoc airport planning adjusted to serve APEC 2027

For 2021-2030, the Civil Aviation Authority of Vietnam proposed bringing forward the investment in a parallel taxiway system and a connecting taxiway north of Runway No. 2 at Phu Quoc International Airport, in order to connect with the aircraft maintenance and repair facility (hangar) planned for the northern area of ​​the airport.

Policy, infrastructure emerge as new advantages in FDI attraction

Policy, infrastructure emerge as new advantages in FDI attraction

From policy and infrastructure to industrial real estate, Vietnam’s FDI advantages are broadening towards a more integrated production ecosystem, offering investors a stronger combination of conditions for high-value, technology-intensive and long-term projects.

Logistics upgrade vital to 1-trillion-USD trade target: experts

Logistics upgrade vital to 1-trillion-USD trade target: experts

As trade expands, systemic bottlenecks across transport networks, warehousing, ports, border gates, and industrial zones are becoming more apparent. Experts emphasise the need to shift from a fragmented, project-by-project approach toward strategic management structured around trade corridors and integrated supply chains.

Ample room for Vietnam, US to deepen cooperation

Ample room for Vietnam, US to deepen cooperation

Do Ngoc Hung, Trade Counsellor and head of the Vietnam Trade Office in the US, said what stands out is not only the growth in trade volume but also the increasingly deep economic ties between the two countries.

Flexible fiscal policy helps drive economic growth

Flexible fiscal policy helps drive economic growth

According to the Ministry of Finance, State budget revenue in the first eight months of 2026 was estimated at 2.02 quadrillion VND (77.7 billion USD), equivalent to 80% of the annual estimate and up 16% year-on-year. Domestic revenue reached 1.75 quadrillion VND, accounting for 86.6% of total revenue and rising 16.6%.

Electronic components are produced at a factory in Hanoi. (Photo: VNA)

Hanoi's imports surge 41% in first eight months of 2026

Hanoi aims to achieve average annual export growth of at least 12% during 2026-30, with the city seeking to diversify export markets, boost high-tech and value-added products and reduce reliance on traditional markets.