A total of 117 trillion VND (5.03 billion USD) worth of corporate bond notes were raised in the first eight months of 2019, according to SSI Securities Corporation’s research unit.

The figure means the successful issuance rate in the first eight months was 90.8 percent and the value of the corporate bond market was equal to 10.2 percent of Vietnam’s total gross domestic product (GDP), SSI Retail Research estimated.
The total value of corporate bond offered in the first eight months was estimated at 129 trillion VND, the SSI unit estimated upon information disclosed on the stock exchanges and companies’ websites.
According to the Ministry of Finance, a total of 224 trillion VND worth of corporate bond notes was raised in 2018, up 94.5 percent year on year. The value of the market last year was 474.5 trillion VND, equalling 8.6 percent of the total GDP and higher than the 6.19 percent in 2017.
Commercial banks were still the biggest issuers, raising total 56 trillion VND – 47.9 percent of the total. Banks were followed by property developers, which raised nearly 37 trillion VND – 31.5 percent of the total, infrastructure constructors (9.2 trillion VND, 7.9 percent), and non-banking financial firms (4.42 trillion VND, 3.8 percent).
Though realty firms ranked second in the list of top issuers, the successful issuance rate of the sector was 77.3 percent – the lowest among those mentioned. Forty-four property firms opened 139 placements to offer 47.8 trillion VND worth of bond notes.
Banks’ bond yield rates were the lowest, fixed and annually-paid. Average per-annum bank bond yield rate was 6.75 percent and average maturity was 3.3 years.
On the contrary, realty bond yield rates were the highest at a per-annum average of 10 percent, which was followed by infrastructure (9.79 percent) and financials (8.64 percent).
According to SSI Retail Research, Decree 163/2018/NĐ-CP dated December 4, 2018 opened the corporate bond market for the business community by reducing the ratio of short-term capital spent on medium- and long-term lending.
The increase of the risk ratio in bank loans for real estate projects motivated companies to raise capital via bond issuance from making bank loans.
In addition, the transparency of information disclosure and more active participation of middle stakeholders like banks and brokerages made corporate bonds more attractive.
However, there are still risks with the local corporate bond market despite good growth in recent years, according to Nguyen Viet Cuong, vice director of analysis centre at Vietinbank Securities Co.
“The biggest risk now is information transparency. In other markets, the role of credit rating firms is quite clear and important because they have various rankings for various types of corporate bond and investor appetite,” he said.
“Therefore, Vietnam will soon have to make space for business credit rating institutions to make the corporate bond market more transparent” and make it a good source of capital for companies beside bank loans, Cuong said.
Though the Vietnamese corporate bond market has made big improvements, it should be noted that commercial banks are still the biggest bond buyers, especially in the real estate sector, while the identity of buyers should be public, Nguyen Duc Hung Linh, director of individual customer analysis and consultancy at SSI Securities Corp, said.
If the role of credit rating firms remained vague, bond buyers, especially individuals, would not be able to find the appropriate yield rates, he said, adding investor protection policies must be improved in the future.
According to economic specialist Bui Quang Tin, CEO of Bizlight Business School, bondholders may face higher risks when they purchase corporate bonds because they have no collateral from the companies.
"The higher the yield rates are, the higher the risks," he said, adding "the major risk lies in true information of firms, which cannot be found publicly and is sometimes hidden from individual investors".
Purchasing corporate bonds may sometimes mean all-in for investors, according to Tin. If the company declares bankruptcy, investors may lose everything so there must be a policy to protect bond buyers from such risk.
By 2030, Vietnam aims to rank among the world’s top 40 in the GII; raise total social investment in R&D to at least 2% of GDP, with non-State funding accounting for over 60%; increase international scientific publications by an average of 10% annually; and raise the number of patent applications and granted patents by an average of 16-18% annually.
The State Bank of Vietnam set the daily reference exchange rate at 25,624 VND/USD on October1, down 3 VND from the previous day.
Quang Ninh's GRDP grew 15.04% in the third quarter, also leading the country.
Vietnam needs flexible incentives and specialised green financial instruments, stronger inter-sectoral coordination, improved local governance capacity and a more complete MRV data system, said Ramla Khalidi, Resident Representative of the United Nations Development Programme (UNDP) in Vietnam.
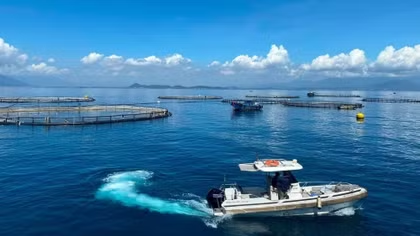
As the country enters a new development phase with greater demands for stronger marine-economy growth, institutional bottlenecks have emerged and need to be addressed.
Experts from the Institute of Vietnam and World Economy under the Vietnam Academy of Social Sciences noted the quality of recent growth as the high growth rate has been recorded against an increasingly higher comparative base.
Vietnam's Halal exports remain modest at around 900 million USD a year, accounting for less than 1% of the global market. Most exports are still raw agricultural and seafood products. Only around 1,000–1,300 Vietnamese businesses obtained or maintained Halal certification during 2024–2026.
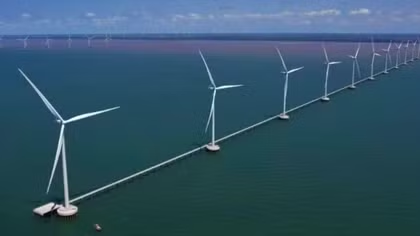
Vietnam needs a comprehensive policy framework to remove legal and procedural bottlenecks and create conditions for offshore wind power projects to access long-term investment capital, helping to unlock the country’s substantial offshore wind potential, said insiders.
Under a decision of the municipal People’s Committee on establishing an inter-agency working group, departments and agencies are responsible for identifying facilities subject to greenhouse gas inventories, developing emissions-reduction plans and studying projects capable of generating carbon credits.
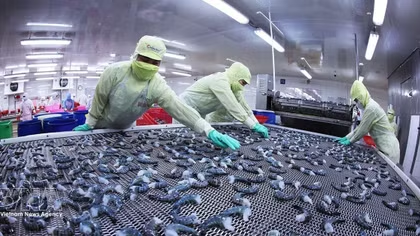
According to data from the Vietnam Customs cited by the Vietnam Association of Seafood Exporters and Producers (VASEP), shrimp exports reached 478.5 million USD in August, up 4.2% from the same month last year. The eight-month total stood at 3.3 billion USD, representing a year-on-year increase of 12%.
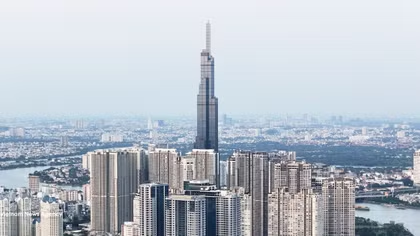
Vietnam is seen as a potential market, with considerable room for growth in real estate, particularly commercial property, compared with some regional markets. Strong Vietnam-Russia ties and opportunities to establish foreign-invested enterprises are also considered favourable for Russian investors.
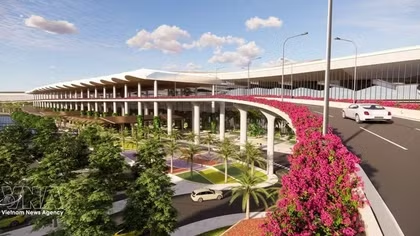
For 2021-2030, the Civil Aviation Authority of Vietnam proposed bringing forward the investment in a parallel taxiway system and a connecting taxiway north of Runway No. 2 at Phu Quoc International Airport, in order to connect with the aircraft maintenance and repair facility (hangar) planned for the northern area of the airport.
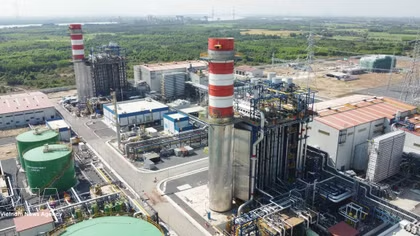
For LNG-fired power to fulfill its role in Vietnam’s energy transition, bottlenecks in institutions, infrastructure, electricity pricing, PPAs, power dispatch and financing must be addressed together.
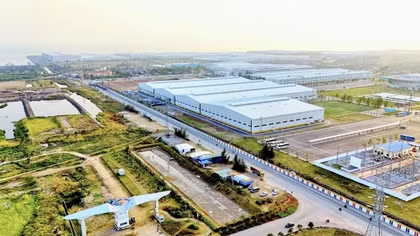
From policy and infrastructure to industrial real estate, Vietnam’s FDI advantages are broadening towards a more integrated production ecosystem, offering investors a stronger combination of conditions for high-value, technology-intensive and long-term projects.
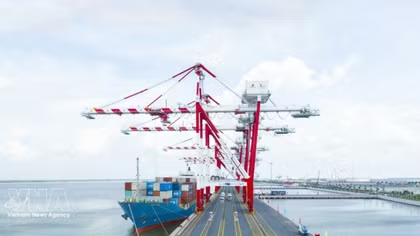
As trade expands, systemic bottlenecks across transport networks, warehousing, ports, border gates, and industrial zones are becoming more apparent. Experts emphasise the need to shift from a fragmented, project-by-project approach toward strategic management structured around trade corridors and integrated supply chains.
The company will buy non-performing loans from credit institutions and foreign bank branches, recover and dispose of debts and collateral, restructure loans and support lenders in resolving bad debts.
Do Ngoc Hung, Trade Counsellor and head of the Vietnam Trade Office in the US, said what stands out is not only the growth in trade volume but also the increasingly deep economic ties between the two countries.
According to the Ministry of Finance, State budget revenue in the first eight months of 2026 was estimated at 2.02 quadrillion VND (77.7 billion USD), equivalent to 80% of the annual estimate and up 16% year-on-year. Domestic revenue reached 1.75 quadrillion VND, accounting for 86.6% of total revenue and rising 16.6%.
Hanoi aims to achieve average annual export growth of at least 12% during 2026-30, with the city seeking to diversify export markets, boost high-tech and value-added products and reduce reliance on traditional markets.
Great reliance on the state budget and conventional bank lending could put considerable pressure on the financial system, making it necessary to develop new and sustainable sources of funding from both domestic and international capital markets.